 Oluwadi
Investigating the Overlooked
Region
What
Who For
Analysis
Oluwadi
Investigating the Overlooked
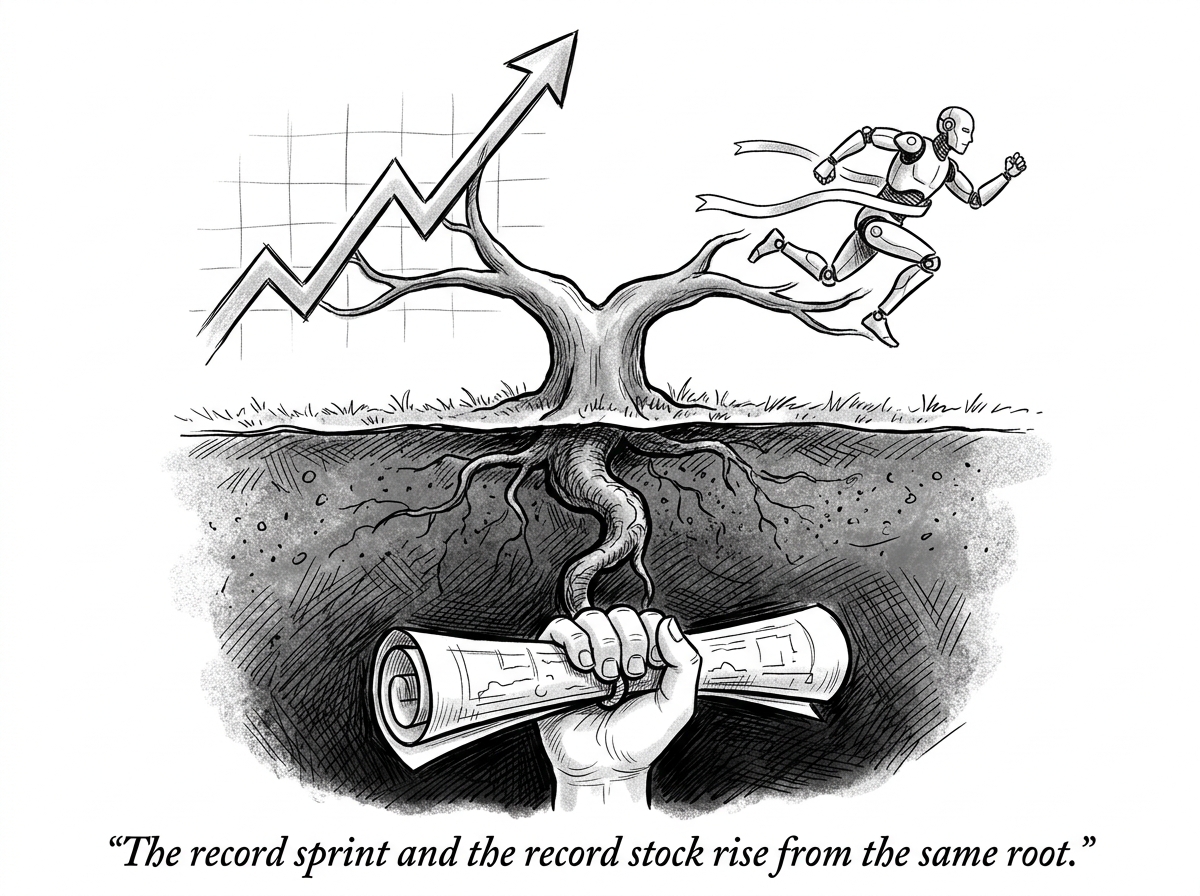
On August 19, 2026, Unitree Robotics began trading on Shanghai's STAR Market under ticker 688836, priced at ¥150.80 a share after an IPO that valued the company at roughly $9 billion -- and immediately surged 629% intraday before closing up 487%, pushing its market value to an estimated $53 billion.[1] Retail demand for the offering was oversubscribed roughly 8,000 times over. Unitree became the first pure-play humanoid-robot maker to list on a mainland Chinese exchange, and the debut was immediately read as a valuation benchmark for the 30 to 50 other humanoid-robotics companies reportedly preparing listings in Hong Kong.[2]
China's 15th Five-Year Plan (2026-2030) names embodied AI and humanoid robotics as a distinct strategic industrial priority -- the first time the category has appeared on its own in a plan of that rank, rather than folded into a broader technology or manufacturing goal.[3] The policy machinery behind that designation is not abstract: a national "Robot+" initiative and an "AI + Manufacturing" roadmap set a target of 100,000 humanoid robots deployed by 2027, backed by an $8.2 billion National AI Industry Investment Fund launched this year and more than $26 billion in additional city-level funds assembled by Beijing, Shenzhen, and other municipalities since late 2024.[4] Local governments layer on their own incentives on top of that -- free land, subsidized office rent, and rebates worth roughly 10 percent of a robot's sale price to buyers.[4] Unitree's IPO is the public capital-markets expression of a policy apparatus that was already running underneath it.
Unitree is a private company that state money has flowed toward. The Beijing Humanoid Robot Innovation Center -- known by its product line as X-Humanoid, maker of the Tiangong robot -- is a different structure entirely: co-founded in 2023 by Xiaomi's robotics arm, Shenzhen-based UBTech, and the state-owned Beijing Jingcheng Machinery Electric Co., with a Beijing municipal investment vehicle joining as a shareholder afterward. The center was designated a national-and-local joint innovation hub for embodied AI in October 2024 and raised a further $100 million in its first outside funding round this year.[5] Its robot, Tiangong Ultra, has spent the past several weeks breaking human world records in public, at a state-organized event: 9.39 seconds in the 100m on the opening day of the second World Humanoid Robot Games in Beijing, then 8.86 seconds three days later -- nearly a full second under Usain Bolt's actual human record -- plus records in the 400m, the 1,500m, and the high jump.[6][7]
Months earlier, on April 19, 2025, Tiangong Ultra had already won the world's first humanoid half-marathon in Beijing -- a genuinely harder test than a 100m dash, and one that shows the limits alongside the headline. The robot finished the 21.0975km course in 2 hours, 40 minutes, and 42 seconds, falling once and needing three battery swaps along the way. The human winner of the same race finished in 1 hour and 2 minutes -- less than half the robot's time. Of 21 humanoid robots entered, only six finished at all, and only four beat the four-hour cutoff.[8] Tiangong Ultra's sprint records are real and independently reported by wire services, not just Chinese state media. So is the fact that a robot built for straight-line speed still can't reliably out-endure an amateur human runner over distance, or stay upright doing it. Both facts belong in the same paragraph.
What actually makes this industrial policy, not a string of unrelated headlines: the state shows up at every layer of the stack at once, not just one. National five-year planning names the sector a priority. Dedicated public investment funds -- national and municipal -- capitalize the companies. Local subsidies lower the cost of building and buying the hardware. A state-linked research center owns and races the robots that generate the viral demonstrations. And a private-market IPO converts the whole apparatus into a tradeable valuation benchmark for everyone else in the sector. None of those five layers depends on the others to exist, but together they explain why a stock surge and a broken world record landed in the same news cycle: they are outputs of the same policy, not a coincidence of timing.
On August 27, 2026 -- eight days after Unitree's Shanghai debut -- Anthropic announced the Model Hardware Standard (MHS), an open specification that does for physical machines what its earlier Model Context Protocol did for software tools: a shared interface letting AI agents read sensors, write to actuators, and safely operate robotic arms, microscopes, and manufacturing equipment without custom integration work for every device.[9] MHS is a research preview, developed with HHMI Janelia Research Campus, and Anthropic plans to open-source the full specification.[10] It is a single private company publishing a voluntary standard that any hardware maker -- Figure, Universal Robots, whoever else adopts it -- can build against. No government fund capitalized it. No national plan named it a priority. It exists because one company decided to build and publish it.
China is not absent from this software layer either, which sharpens the comparison rather than erasing it. In February and March 2026, China's Ministry of Industry and Information Technology released the country's first national standard system for humanoid robotics and embodied AI, built with more than 120 research institutions, enterprises, and industry users under a government-organized technical committee, covering everything from core computing to safety and ethics.[11] The same period produced China's first robot operating system, built on the Huawei-linked OpenHarmony platform. Both countries now have a software-control layer for humanoid robots. The difference is who wrote it: in the US, a private company published a voluntary specification other companies can choose to adopt; in China, a ministry organized 120 institutions to produce a mandatory national standard. Hardware and software both show the identical asymmetry -- state-directed and centrally coordinated on one side, privately built and voluntarily adopted on the other.
Why does this matter? Humanoid robotics is still a young enough technology that no one knows yet which capital-formation model actually produces working robots faster -- state-directed full-stack coordination, or private companies competing to get voluntary standards adopted. What's no longer ambiguous is that both models are now fully engaged, in public, at the same time, on the same technology. Unitree's IPO and Tiangong Ultra's broken records are not two separate China stories. They are the same industrial policy, viewed from two different desks -- and the US is running its own version of the same race from a desk that looks almost nothing like it.
By late August 2026, Unitree's shares had fallen roughly 45% from their post-IPO peak, erasing an estimated $30 billion of the paper valuation the debut created and pulling the company's market value down from a high near $66 billion.[12] The retreat came alongside Unitree's own prospectus disclosure that adjusted net profit fell 53% to roughly $5.95 million in the first quarter of 2026, and a persistent commercial reality: the robots draw crowds for running, dancing, and martial arts demonstrations, but have had little success in broader commercial deployment. Abraham Zhang, chairman of venture capital firm China Europe Capital, attributed the debut-day spike itself to "a desire by some to pump up the shares so as to dump them later at lofty prices." Founder Wang Xingxing has downplayed near-term expectations while still arguing robots are approaching a "ChatGPT moment."[13]
This complicates the piece's own framing in a way worth stating plainly rather than smoothing over. The five-layer industrial-policy apparatus this piece described -- national planning, dedicated investment funds, local subsidies, a state-linked research lab, and a public listing -- explains how Unitree got to a 629% debut surge. It does not, on its own, explain what happens after the surge. Retail investors bid the stock up on the policy signal; the market has since spent two weeks pricing in the gap between that signal and Unitree's actual commercial traction. Industrial policy can manufacture a listing-day valuation. It has not yet manufactured a profitable, broadly deployed product -- and the stock's round-trip is the clearest evidence yet that investors have noticed the difference.