 Oluwadi
Investigating the Overlooked
Region
What
Who For
Analysis
Oluwadi
Investigating the Overlooked
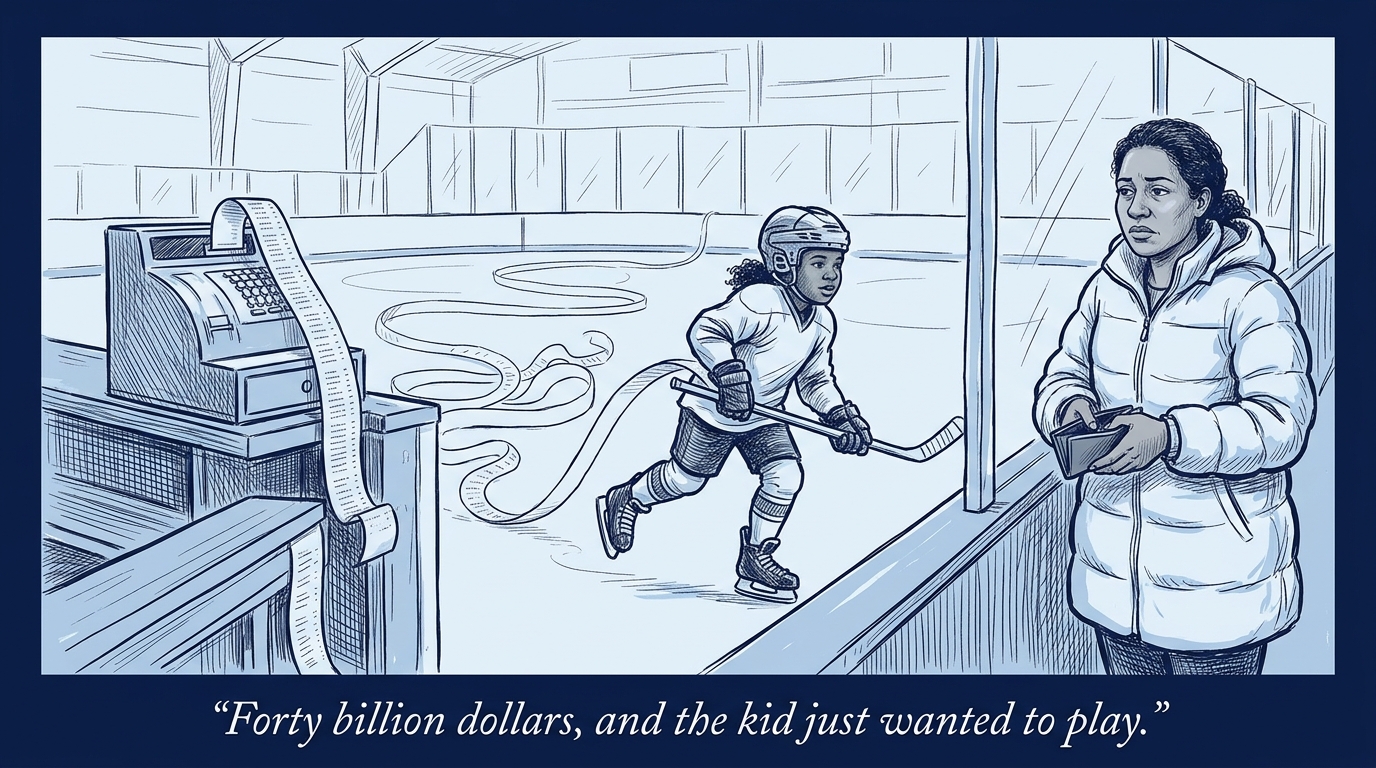
Youth sports in America is now a $40 billion-a-year industry -- nearly double the NFL's own annual revenue -- and the average American sports family spent $1,016 on their child's primary sport in 2024 alone, a 46% jump since 2019.[1] Private equity noticed. Over the past decade, PE firms have bought up rinks, apparel makers, tournament operators, training academies, and the streaming rights to watch a kid's own game, turning what used to be run by a local parks department or a volunteer league board into a portfolio of consolidated, fee-generating assets.
Municipal parks and recreation budgets took real hits after the 2008 financial crisis and again during the pandemic, and private capital moved into the gap that public funding left behind.[2] The buyouts since have been large and specific: in 2023, the private equity firm then known as BPEA EQT bought the sports-education institution IMG Academy for $1.25 billion; in 2024, KKR acquired Varsity Brands -- the dominant name in cheerleading and school sports apparel -- from Bain Capital for $4.75 billion, taking on $2.4 billion in debt to fund the deal.[3] Varsity has since settled two separate antitrust lawsuits over its market power: $82.5 million to a class of "indirect consumers" and a further $43.5 million to independent all-star cheer gyms that alleged the company used its dominance to squeeze them out.[3]
Black Bear Sports Group, founded in 2015 by Murry Gunty's private equity firm Blackstreet Capital, is now the country's largest hockey rink operator -- 42 rinks across 11 states.[4] One of its first moves after each acquisition was a new streaming policy barring parents from broadcasting, livestreaming, or recording their own children's games or practices, citing "privacy concerns," while selling its own official stream through Black Bear TV at $14.99 per game or up to $50 a month for premium league access.[4] Connecticut Senator Chris Murphy -- a hockey dad himself -- has said he was told his own child's team would lose standing points if he livestreamed a game.[5] Black Bear backtracked publicly in November, clarifying its contracts to respect families' right to record their own kids play.[4]
Murphy and Pennsylvania Representative Chris Deluzio introduced the bicameral Let Kids Play Act, co-led in the Senate by Cory Booker, which would treat any private equity firm trying to invest in a youth sports league, facility, tournament, or targeted tech platform as a "vulture investor" by default until proven otherwise -- barring the investment, forcing existing PE holders to divest within two years, requiring reimbursement of previously collected "junk fees," and making the investors personally liable for infractions that occur under their ownership.[5] Murphy has said he intends to build bipartisan support for a version of the bill in the next Congress.[5]
These are two different stories, not one story wearing two costumes, and worth naming as such rather than flattening together: private equity treats existing youth-sports infrastructure as a financial asset class to be bought, consolidated, and fee-optimized. NHL franchises entering a local market are doing something else -- building out territory, often with direct municipal financing help, years before any PE firm shows up. Different actors, different incentive structures, different origin points. What they share is not a mechanism. It's an outcome: youth hockey specifically getting more expensive with no improvement in the actual product, because the family paying for ice time has no real say in either process.
The Dallas Stars now control 10 of the 13 ice rinks in the Dallas-Fort Worth area and own three of them outright, built through financing deals struck with five local governments between 1999 and 2011: each city put up roughly $10 million or more to build a rink, then leased it exclusively to the Stars, who agreed to repay the cities in rent over 20 to 30 years -- public capital, private control.[8] Families and independent coaches now describe a near-monopoly: registration fees raised while ice hours were cut, and retaliation against coaches who defect to other rinks or parents who criticize the franchise publicly.[8] In Las Vegas, the Golden Knights followed a similar path -- Southern Nevada had three community rinks when the franchise was granted its expansion license in 2016; it has since helped grow that to seven, including facilities built by owner Bill Foley's own entertainment group. After the team's operator took over Fiesta Ice Arena in late 2023, independent youth hockey organizations say their weekly ice time was cut as Golden Knights-affiliated Junior teams expanded into the same building, prompting public accusations of "a huge conflict of interest."[9]
What makes this version harder to see coming, not easier, is the civic goodwill attached to it. A private equity firm buying rinks reads as exactly what it is. An NHL franchise building rinks and running youth programs reads as investment in the community -- right up until families notice their registration fees climbing and their ice hours shrinking, run by the same organization that also controls the only other rinks in town.
Why does this matter? There is little evidence that any of this consolidation actually produces better athletes. A review of 93 studies covering more than 62,000 young athletes found early sport specialization associated with higher injury risk, worse functional performance, and no reliable benefit to eventual success -- specialized youth athletes report hip or groin pain at 63% versus 53% for their multi-sport peers, are more likely to quit a sport due to injury (68% versus 55%), and undergo surgery at nearly double the rate; players who eventually reached the NFL had up to a 24% lower injury risk if they played multiple sports in high school instead of specializing early.[6] The direct effect that is well documented is financial: a New York Life survey of over 1,000 parents found average annual youth-sports spending near $3,000, 64% reporting rising costs, and one in five parents who have already reduced or ended a child's participation because of it.[7] A public good with a genuine local-access mission -- kids playing organized sports regardless of family income -- was left exposed by a funding gap, and private capital filled it exactly the way private capital fills any gap: by extracting a return from whoever is left standing when the public money runs out. In this case, that's mostly parents, paying per-game streaming fees to watch a game their own child is playing in. It's the same mechanism now reshaping a far bigger institution at the same time -- American higher education, where a demographic and confidence collapse in the traditional four-year pipeline is being met by private employers building their own alternative credentialing systems instead.
In May 2026, Varsity settled a third antitrust case -- with the Open Cheer & Dance Championship Series and Deep South Cheer -- just two weeks before it was set to go to a federal jury in Texas, on claims that its practices amounted to illegal price-fixing. It was the fourth consecutive time Varsity avoided a jury verdict on antitrust claims, following the $43.5 million settlement with independent gym owners in 2023 and the $82.5 million settlement approved in 2024 already cited in this piece. The May 2026 plaintiffs had sought more than $10 million in damages plus injunctive relief; settlement terms were not disclosed. The U.S. All Star Federation remains the sole co-defendant still fighting the underlying claims.[10]
The valuation trajectory behind that pattern is worth naming in full, because it is the clearest available illustration of what "consolidated, fee-generating asset" means in practice. Varsity has changed private-equity hands four times since 2010: OnCap bought it for $184 million that year, Charlesbank bought it for $1.5 billion in 2014, Bain Capital bought it for $2.5 billion in 2018, and KKR bought it for roughly $4.75 to $4.8 billion in 2024 -- a 26x increase in headline value across four ownership changes in fourteen years, with the same CEO, Adam Blumenfeld, staying on through all four. KKR's own partner has said the fund wouldn't have made the investment without believing it could double or triple the business again from here.[11]
Read together, the settlement pattern and the valuation curve are the same mechanism from two sides. Each successive owner bought a business whose market position was, in part, defended through the practices now drawing repeat antitrust litigation -- and each successive owner sold it for more than they paid, with the litigation cost treated as a manageable line item rather than a deal-breaker. Four ownership changes in, the settlements keep coming and the price keeps climbing regardless.
James Lessnick coaches youth hockey in Las Vegas -- inside the exact market this piece already documents, where the Golden Knights' operator took over Fiesta Ice Arena in late 2023 and independent teams saw their ice time cut. He read this piece and confirmed the mechanism from the inside, not from the outside: "being in the community, unfortunately I know all about this. Especially what the Dallas Stars did to community youth sports, and my son and I are living the increases brought about by the Golden Knights." Asked to separate the two mechanisms the piece already distinguishes -- private equity roll-ups and NHL franchise expansion -- he drew the same line unprompted: "having an NHL team come to town and VC getting involved... has just gotten more expensive for no good reason."
That's the $3,000-a-year statistic and the one-in-five-families-who-cut-back statistic above, from the inside of a single family instead of a survey instrument. The mechanism doesn't stay abstract at the level where someone actually has to decide whether the increase is worth paying.
A friend of the owner coaches high school football -- a different sport, a different region, the same pattern. The piece above documents hockey specifically because hockey is where the rink-ownership and streaming-rights mechanisms are most visible, but the underlying cost curve isn't sport-specific. It shows up in football programs, in travel-team fees, in strength-and-conditioning work parents now pay for directly rather than getting from a school program -- youth sports' own $40 billion figure is an aggregate precisely because no single sport carries the whole number.
It also isn't a story that only happens to someone else's family. Both of the owner's own children play high school sports, and this past summer his household paid directly for a private strength and conditioning trainer for one of them -- the exact category of out-of-pocket, parent-funded cost the piece's own survey statistics describe in aggregate. The mechanism this piece documents at the level of private equity firms and NHL franchises resolves, for almost every family with a kid in organized sports, to the same plain fact: all of it is money, coming from somewhere, whether the family notices the industry consolidating around it or not.
The owner, who built this site, has his own before to set against everything above. His father ran the Police Athletic League program in Pleasantville, New Jersey and coached in it himself -- a municipal police department running organized sports for the town's kids as part of the job, not a business. The owner played peewee football and baseball through it. No fee, no equipment package to buy from the league, no streaming subscription to watch his own games. A public institution simply provided it, the way parks and rec budgets used to before the cuts described above opened the door private capital walked through.
That's the actual distance the piece's numbers are measuring. Not "sports cost more than they used to" as an abstract inflation statistic, but a public good that existed inside one family, in living memory, replaced within a single generation by a $40 billion private industry -- and the replacement isn't hypothetical to the family that lived both sides of it.